

Damian Michael: Building South Africa’s Digital Backbone One Decimal Point at a Time
Prior to the emergence of terms such as artificial intelligence, cloud computing, and cybersecurity, Damian Michael realized the importance of technology in creating trust. At the very beginning of his career, he worked as a field technician where he witnessed how the lack of proper infrastructure had impacted both businesses and public institutions. Instead of seeing this problem as a part of normal business in the industry, he realized that there was an opportunity to do something different. This vision resulted in the creation of Innovo Networks, which is an organization that provides ICT solutions that are integrated and reliable. Now, as the Managing Director, Damian ensures that this approach to business is sustained through his belief in governance and innovation. What Damian’s journey has been about is more than business success; it has been about making business value from everyday challenges. Discover how Damian Michael is redefining ICT leadership by proving that lasting innovation begins with trust, governance, and purpose. From Field Technician to Founder Michael’s path into technology leadership began with a simple observation. Early in his career, keeping mission-critical systems running across Cape Town, he watched how fragmented, unreliable ICT held businesses and public institutions back. He noticed a gap between what organizations were sold and what they needed, and that gap became the catalyst for Innovo Networks. He built the company as an operator owning connectivity, voice, and security end-to-end, backed by partnerships with Vodacom, Liquid Telecoms, and other major providers. Measurable impact motivates him most, whether helping a municipality serve citizens better or a business operate more securely. “Today, I see AI adoption outpacing governance, and wants Innovo Networks to prove organizations can harness AI without sacrificing the discipline that earns lasting trust,” he says. Innovation Anchored in Reliability That discipline shapes how Michael balances innovation against sustainability. He tests every idea against one question: Does it create measurable value, or is it just interesting? He treats innovation for its own sake as a distraction, building around customer needs rather than chasing trends. The company’s Video PBX platform illustrates this. Running on Huawei Cloud infrastructure for roughly eight years, it has maintained a measured 99.99 percent uptime while serving more than a thousand users since 2013, a record that gives Innovo Networks license to introduce new capabilities without gambling on the basics. AI-driven automation, when layered into a client’s environment, sits atop that foundation rather than replacing it. Continuous engagement has shaped sector bundles such as Bonded Internet, Finance, and Health Shield, built to solve real operational problems, not sell isolated tools. A Milestone Measured in Decimals Asked about his career’s most transformative milestone, Michael points to the quiet accumulation of trust rather than a single dramatic event. Building Innovo Networks into a strategic partner across financial services, healthcare, and the public sector, anchored by that eight-year uptime run, taught him that credibility is earned in decimals rather than press releases. A harder lesson arrived through a contractual dispute, when a client’s own conduct effectively constituted acceptance of delivered goods, yet Innovo Networks absorbed the loss, proof that goodwill cannot substitute for airtight commercial terms and clearly defined agreements. The journey taught him that entrepreneurship is not about having every answer, but about assembling the right team and recognizing that people remain the true foundation of an organization. Betting on AI, Built on Governance Asked which trend shape business over the next five years will most, Michael answers without hesitation: artificial intelligence, though never as a standalone capability. Its impact depends on the foundation beneath it: cloud computing for scale, cybersecurity to protect data, and governance to keep AI accountable. Innovo Networks built its own AI governance framework, aligned with the IBM AI Risk Atlas and covering drift monitoring, hallucination controls, prompt injection defenses, and POPIA compliance, before allowing agentic tools near client workflows. Michael believes the businesses that thrive ahead will combine human expertise with AI-driven insight responsibly enough to prove their systems remain accountable and safe by design. Leading Through Trust and Accountability Michael’s leadership philosophy rests on trust, accountability, and continuous improvement. He believes people perform best when empowered to own their responsibilities, and that innovation often comes from whoever sits closest to the problem, not the top of an organization chart. Accountability converts trust into performance: every proposal carries agile sprint backlogs, risk registers, and RACI matrices, because a responsibility not written down is not truly real. That discipline enables collaboration over territorial behavior, since everyone knows where their piece of a project ends and a colleague’s begins. Strong cultures, he insists, are built on people trusting the system enough to take risks. The Test That Reshaped His Approach The most significant test of Michael’s resilience was commercial rather than technical. Innovo Networks found itself formally pursuing a Letter of Demand after a client’s own asset-handling conduct had legally constituted acceptance of delivered stock yet left the company absorbing the loss. Being contractually correct still meant a difficult process, forcing him to confront how heavily he had relied on goodwill over a watertight process. That experience taught him to combine data-driven decisions with strategic intuition, since leaders cannot wait for perfect information. Every engagement carries defined commercial terms upfront, whether a 36-month opex arrangement or a 12-month capex model. Innovation Tied to Client Outcomes Michael keeps innovation tethered to client value by leading with business outcomes rather than technology, understanding strategic objectives before recommending any solution. FinanceIQ for financial services firms and HealthShield for healthcare practices consolidate what each sector genuinely needs under one accountable relationship. FinanceIQ pairs connectivity, cybersecurity, and managed ICT support with Innovo’s own AI governance layer, GovernAI, so clients purchase assurance as much as infrastructure. Long-term relationships depend on trust, with clients wanting a partner who anticipates needs and offers honest guidance, reflected in Innovo’s partnerships with Vodacom and Liquid Telecoms. Rethinking Digital Transformation If Michael could correct one misconception about digital transformation, it is the assumption that it is primarily a technology project, where buying
The Role of Leadership Strategies in Managing Business Change
Guiding Organizational Change Change is one of the few constants in business. Markets evolve, industries are disrupted, customer expectations shift, and the internal dynamics of organizations themselves require regular recalibration. For most businesses, the question is not whether change will arrive but whether they will be ready for it when it does. Readiness does not happen by accident. It is built through deliberate leadership that knows how to manage transition, maintain momentum, and bring people through uncertainty without losing the trust or the direction that any organization needs to function well. Leadership strategies are what give this kind of readiness its structure, and their role in managing business change effectively is one of the most important things any organization can invest in getting right. Why Change Fails Without the Right Leadership The research on organizational change is consistent on one point. Most change initiatives do not fail because the idea behind them was wrong. They fail because the leadership of the change was inadequate. Poor communication, insufficient support for the people being asked to work differently, resistance that was predictable but not prepared for, and leadership behavior that contradicted the changes being asked of everyone else are all failure patterns that repeat themselves across industries and organization sizes. Leadership strategies that are built around the realities of how change actually affects people tend to produce very different outcomes. They account for the fact that change creates anxiety, that people need more than a logical case to shift long-standing habits, and that the gap between announcing a change and embedding it into how the organization actually works requires sustained, patient, and deliberate leadership effort. Setting Direction with Honesty The first thing people need when change is coming is clarity. What is changing, why it is changing, what the expected outcomes are, and what the process of getting there will look like. In the absence of this information, people fill the gap with speculation, and speculation in uncertain times tends to run negative. Rumors take hold, anxiety rises, and energy that should be directed toward the change gets consumed by worry about what it might mean. Leadership strategies that prioritize honest and clear communication from the outset significantly reduce this dynamic. Leaders who are willing to share what they know, acknowledge what they do not yet know, and commit to keeping people informed as things develop build the kind of credibility that carries an organization through the messiness of genuine change. Clarity is not always comfortable, but it is far more productive than ambiguity. Managing the Human Side of Change Business change is ultimately experienced by people, and people do not respond to change in a linear or purely rational way. Even changes that are objectively beneficial require people to let go of familiar ways of working, to develop new skills, and to rebuild their sense of competence in a context that may feel uncertain and unfamiliar. This emotional dimension of change is one that leadership strategies need to account for explicitly rather than treating it as a secondary concern. Leaders who acknowledge this honestly, who create genuine space for people to process the difficulty of change, and who provide the support and development needed to help people succeed in the new environment tend to move their organizations through transition with far less friction and far less talent loss than those who treat the human response to change as a problem to be managed away. Maintaining Stability While Driving Change One of the most difficult balancing acts in leading business change is maintaining enough stability to keep the organization functioning effectively while simultaneously driving the transformation that is needed. An organization in the middle of significant change still has customers to serve, commitments to meet, and day-to-day performance to maintain. Allowing the change process to destabilize operations entirely is not a price worth paying. Leadership strategies that navigate this balance effectively tend to sequence change thoughtfully, protect the elements of organizational functioning that need to remain stable, and create clear boundaries between what is changing and what is not. This clarity allows people to understand what they can rely on even as other things shift around them. Sustaining the Change Once Made Many organizations succeed at launching change and struggle at sustaining it. The initial energy and attention that come with a significant transformation are hard to maintain over the months and years it takes for new ways of working to become genuinely embedded in how the organization operates. Without deliberate effort to sustain the change, old patterns reassert themselves and the investment made in transformation fails to produce the lasting results it was designed for. Leadership strategies that address this sustainability challenge build reinforcement mechanisms into the change process from the beginning. Conclusion Managing business change well is one of the most demanding things any leadership team attempts. Leadership strategies that are honest, people-centered, clear about direction, and deliberate about sustaining what has been built are the ones that produce change that sticks. Organizations that invest in developing these strategies, and in the leaders capable of executing them, are the ones most likely to navigate the inevitable disruptions of business life with their performance and their people intact.
How Executive Strategy Aligns Business Priorities with Growth
Building Strategic Alignment Every business has more tasks than it can finish at once. Customers want attention and teams ask for resources, while new openings appear faster than anyone can study them. Without a clear sense of direction, effort gets spread thin and growth slows. Executive strategy is what gives that effort a shape. It tells an organization what matters most and what can wait. When it is done well, daily work and long-term goals pull in the same direction. This is not a matter of working harder. It is a matter of pointing the work at the right target, and that choice belongs to the leaders who set the course. Why Priorities Need a Clear Order Not every goal deserves equal weight. Some tasks protect the business, while others help it expand. Leaders who treat every goal as equally urgent end up with tired teams and thin results. Setting an order is hard because it means saying no to things that sound attractive. Even good ideas must sometimes wait, and that is a difficult message to deliver. A good executive strategy makes that order visible. It explains why one priority comes before another, so people do not have to guess. It also gives leaders a fair way to judge new requests as they arrive. When staff understand the reasoning, they accept trade-offs more easily and make better choices on their own. Linking Daily Work to Long-Term Growth Growth rarely comes from one large move. It builds from many small decisions made well over time. The danger is that daily work can drift away from the larger aim. A team may stay busy and still contribute little to where the business wants to go. Executive strategy closes this gap by connecting each department’s tasks to a shared purpose. Each team can then ask a simple question: does this work move the business forward? If the answer is unclear, the work deserves a second look. Over time, this habit trims away tasks that no longer serve any real need. Making Decisions with Good Information Smart planning requires proper information. Proper planning requires clarity of vision. The management must be aware of the company’s performance and what the customer says about it. In addition, it is important for them to know what factors lead to increased costs. Information alone is not enough, though. It must be read with care. A sudden change in results may be a passing event or a sign of a deeper issue. Experienced executives learn to distinguish between the two by asking questions prior to making a decision. The temptation to respond to any change should be resisted. Balancing Today’s Needs with Future Plans Every business must earn today while preparing for tomorrow. Focus too much on the present, and the company may fall behind as conditions change. Look too far ahead, and current operations may suffer. Neither extreme serves the business well. The balance is difficult to hold. A thoughtful executive strategy treats both needs as real. It sets aside resources for steady operations and for work that will pay off later. This takes patience, because future-focused work often shows little result at first. Leaders must be willing to defend it during slow periods. Building Agreement Across the Organization A plan that only the top team understands will not go far. Strategy works when people at every level know their part in it. That requires regular and honest communication, not a single announcement made once and forgotten. Shared understanding also reduces friction, since fewer people work at cross purposes. The strategy should be explained to everyone in plain terms that they can understand. At the same time, the leaders should take into account the concerns that come up during the discussion. This is because the people who implement the strategy have better visibility about some issues than the senior leaders. Reviewing and Adjusting Over Time No plan stays correct forever. Markets move and customer needs change. Competitors adjust as well, and what worked last year may not work now. This is true for large companies and small ones alike. Ignoring change does not stop it, and the business simply meets it unprepared. Regular review keeps strategy honest. Leaders should check whether the chosen priorities still produce the expected results. If they do not, changes should be made without delay or defensiveness. A strong executive strategy is not rigid. It holds firm on purpose while staying flexible about method. In Summary When priorities and growth goals line up, a business gains a calm kind of strength. Decisions come faster because the direction is already known. Teams waste less time on competing demands, and leaders spend less effort settling disputes. Growth that comes from this alignment tends to last. It rests on clear choices rather than luck or sudden bursts of activity. In the end, executive strategy is less about bold announcements and more about disciplined, steady judgment. Businesses that practice it do not simply grow larger. They grow with purpose, and that makes their progress easier to protect.
The Most Inspiring Icon to Watch in 2026
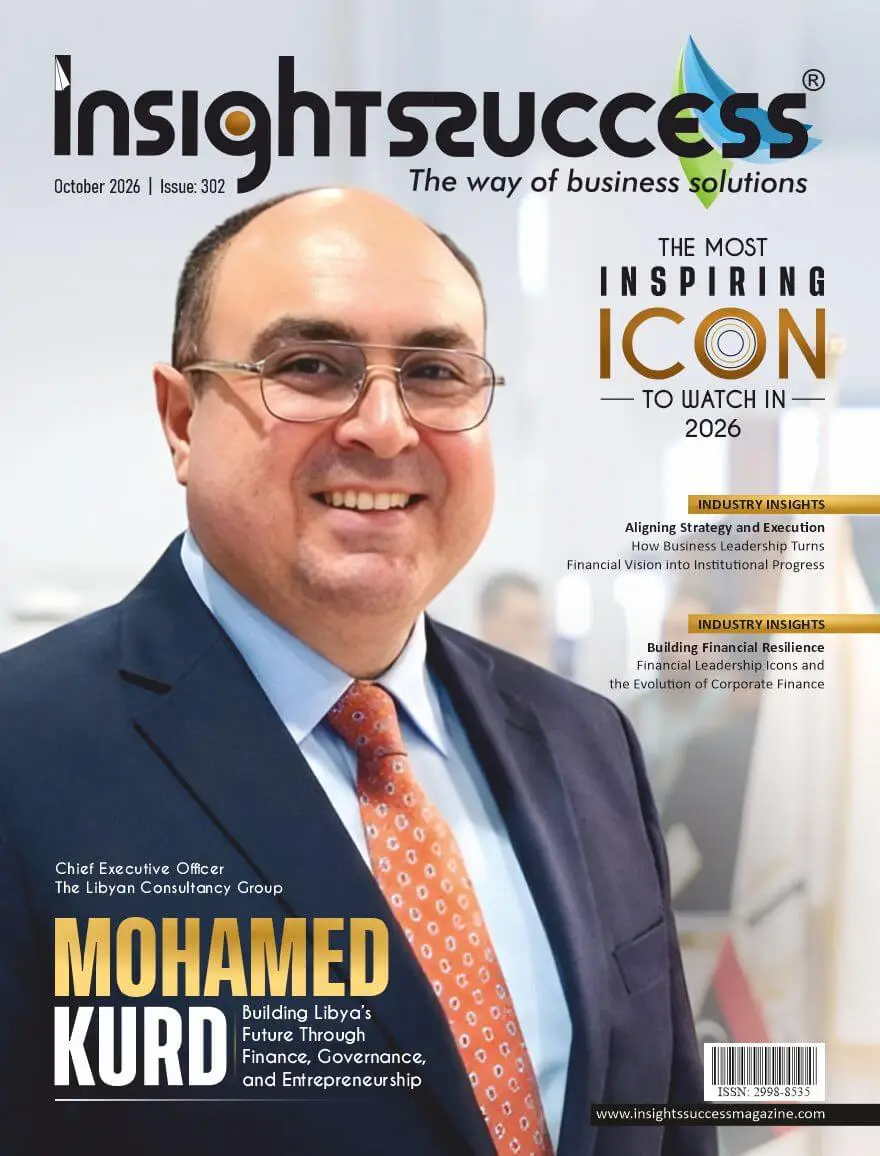
The Most Inspiring Icon to Watch in 2026 Recognizing an inspiring icon advancing Libya’s economic future through finance and entrepreneurship. This edition explores Mohamed Kurd’s work in governance, institutional development, financial accountability, youth empowerment, and sustainable economic growth. Digital Link Quick highlights Quick reads
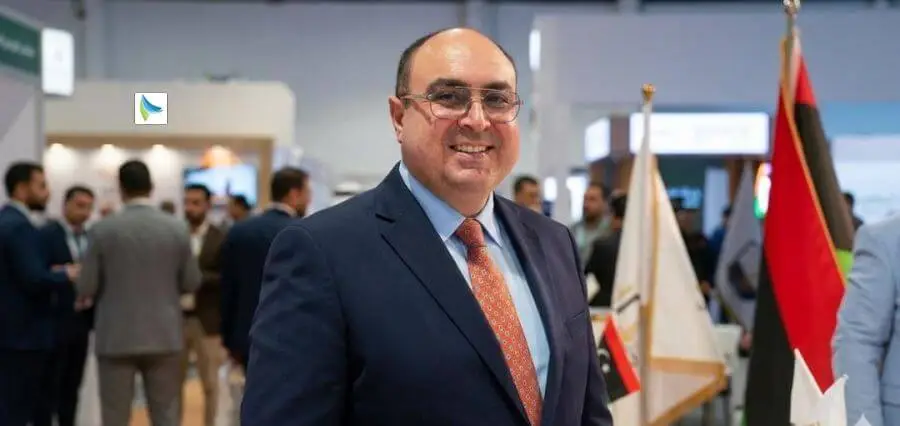
Mohamed Kurd: Building Libya’s Future Through Finance, Governance, and Entrepreneurship
Nations build lasting prosperity through institutions, not just resources. The quality of financial systems, governance structures and entrepreneurship ecosystems determines whether an economy can translate its potential into opportunity for the people within it. In emerging markets, this work is especially consequential. Where institutions are young, financial standards are still maturing, and investment depends heavily on trust, the professionals who bring discipline, transparency, and international expertise to local realities play a role that extends well beyond their immediate responsibilities. Libya sits at exactly this inflection point. A country with significant resources and a generation of talented young people looking for pathways to build, invest, and contribute. What it needs are leaders willing to close the gap between international standards and local practice, one institution, one entrepreneur, and one properly governed balance sheet at a time. Mohamed Kurd, Chief Executive Officer of The Libyan Consultancy Group, has built his career around exactly that purpose. His path across audit, corporate finance, banking, consultancy, and public institutional leadership reflects a consistent conviction: that sound financial foundations are not simply a technical requirement. They are the starting point for everything a society wants to build. From Finance to Institutional Development Mohamed is a Libyan Chartered Accountant, finance executive, and banker whose career has been shaped by one conviction: “Sound finance is the foundation on which institutions, businesses, and nations are built.” He grew up in Libya and earned his Bachelor’s degree in Accounting from Garyunis University in Benghazi in 2006. His career began at PricewaterhouseCoopers in Tripoli as a Senior Associate, where he audited financial statements, tested internal controls, carried out due diligence and valuation assignments, coached audit teams, and worked on judicial cases requiring an independent professional conclusion. He later served as Chief Accountant at Al Mansoori Specialized Engineering in Abu Dhabi and Finance Manager of Schindler Elevator Corporation in Benghazi. He spent more than six years with Sacyr Construcción in Doha, first as Accounts Manager on a USD 1.67 billion joint-venture portfolio and later as Finance Manager on a USD 0.52 billion portfolio. He also served as Financial Controller for Stichting SPARK’s UKAID-funded programme, helping establish the Benghazi Entrepreneurship Centre. He continued learning through an M.Sc. in Accounting and Finance from the University of Western California, an MBA from Rome Business School, and an Executive Master in Marketing & Sales from SDA Bocconi School of Management. He also holds more than fifteen international professional qualifications, including ACCA, DipIFR, Certified CFO, CPFA, and ACPA. Today, he serves as General Manager of the National Entrepreneurship Council and Founder & CEO of The Libyan Consultancy Group. He previously served as Chairman of the Board of Mediterranean Bank. His family, friends, and mentors have remained central to his journey. From Numbers to Institutional Development Mohamed’s profession began with a fascination for the story behind financial accounts. At PwC, he learned to read those stories critically. In the Gulf, managing large construction portfolios taught him to build budgets, control cash flow, negotiate with banks, and implement IFRS-aligned processes that turned financial information into a tool for decision-making. A question stayed with him: how could this knowledge serve Libya? He saw that many Libyan institutions and businesses needed stronger governance, reporting standards, and financial discipline to attract investment and grow sustainably. His work as a consultant to the Central Bank of Libya on the unification project led by UNSMIL and executed by Deloitte, and as a Risk and IFRS Implementation Consultant to Bank of Commerce & Development, reinforced this understanding. This became the idea behind The Libyan Consultancy Group, founded in 2022 with offices in Tripoli and Benghazi. TLG offers financial advisory, IFRS implementation, risk management, corporate governance, due diligence, and forensic accounting services to banks, companies, and public institutions. Its purpose is to bring international standards to local realities with an understanding of the Libyan and MENA context. The same purpose connects to his role as General Manager of the National Entrepreneurship Council since 2023. His work focuses on building an ecosystem where young Libyans can turn ideas into viable enterprises. His time as Chairman of the Board of Mediterranean Bank added responsibility for steering a financial institution at the highest level of governance. His professional path has therefore moved across audit, advisory, corporate finance, banking, consultancy, entrepreneurship, and public leadership. Each stage has added another perspective to his understanding of how financial systems, institutions, businesses, and people are connected. His work began with numbers, but its purpose is people: “Stronger institutions, more transparent markets, and more opportunities for the next generation.” An Appetite for Long-Term Business Value Mohamed’s appetite for business is rooted in the belief that “Enterprise, when built on integrity and sound financial foundations, is a powerful engine of development.” He is interested in creating value, whether by turning around underperforming operations, building an institution, or helping an entrepreneur transform an idea into a sustainable company. His Gulf experience showed him how large organisations succeed or fail through budgeting, cash management, and risk controls. Overseeing finance for projects worth more than USD 2 billion taught him how financing facilities and carefully structured subcontracting could protect millions in value. Founding The Libyan Consultancy Group became a natural next step. As an entrepreneur, He experienced the challenges faced by clients, including winning trust in a young market, recruiting talent, and investing ahead of revenue. He sees opportunities in reforming banks, formalising family businesses, building entrepreneurship ecosystems, and connecting local companies with international partners. His Executive Master in Marketing & Sales at SDA Bocconi reflects his belief that strong finance must be matched with the ability to grow markets and customers. He is not interested in innovation simply for its own sake. He evaluates opportunities through their ability to create sustainable value and support organisations over time. Above all, he has a long-term appetite for business. He measures success over time, focusing on institutions and businesses that can continue thriving because they were built properly from the start. A Passion for Strong Institutions and Young Entrepreneurs
How Business Leadership Turns Financial Vision into Institutional Progress
Aligning Strategy and Execution Every institution starts with a picture of what it hopes to become. In the early days, that picture is only a set of hopes held by a small group of people. It has no staff and no budget yet. Money is what moves it from paper into daily life, and the way that money is planned and spent decides how far the picture can go. But a financial vision on its own does very little. A written plan cannot make a hard choice, and a target cannot explain itself to a worried team. The vision needs people who can explain it and act on it with care, day after day, even when conditions are far from ideal. That is the work of business leadership, and it shapes whether an institution simply survives or truly moves forward. Many organizations hold a strong vision and still fall short. The reason is seldom a lack of ideas. More often, the vision never travels from the top of the organization to the people who carry out the work. Starting with a Clear Vision A financial vision is more than a budget. It describes where an institution wants to stand in the years ahead and what resources it will need to reach that place. Without this clarity, spending becomes scattered and goals drift. Strong business leadership begins by putting the vision into plain words that everyone in the organization can understand. When people understand the purpose behind financial choices, they make better decisions in their own roles. A manager who knows the long-term aim will weigh a small expense differently from one who sees only a line on a report. Turning Plans into Steady Action A vision is easy to admire and hard to carry out. The gap between the two is filled by planning. Leaders must break large goals into smaller steps and give each step an owner. They must also decide what comes first and what can wait. This is where discipline matters. Good business leadership asks hard questions before money is committed. Will this choice support the larger aim? Can the institution sustain it over time? Such questions slow the process a little, but they prevent costly mistakes later. Building Trust Through Honest Communication Trust is the quiet foundation of any institution. People from employees to partners to the general public expect the finances to be managed with integrity. It is through transparency in communication of both success and failures that this trust is gained. Hiding problems rarely works for long and it damages confidence when the truth comes out. Open communication also brings better ideas. People closer to daily work often see waste or opportunity before leaders do. When they feel safe to speak, the institution learns faster. Business leadership that listens is far more effective than leadership that only gives orders. Balancing Caution with Ambition Every financial plan carries risk. Too much caution can leave an institution standing still while others move ahead. Too much ambition can strain resources and put its mission in danger. The task of leaders is to find a sensible middle path. That path is rarely fixed. Markets shift and public needs change. Leaders who review their plans on a regular basis can adjust without panic. They treat a change in direction as part of good management, not as a failure. Here, business leadership shows its value by keeping the institution steady while still allowing it to grow. Developing People Who Carry the Work Forward Progress that depends on one person does not last. Institutions grow stronger when leaders train others to take on responsibility. This means sharing knowledge and giving younger staff real tasks, even when mistakes may follow. Financial skill is part of this training. Every capable manager should understand how money flows through the institution and why certain limits exist. When that understanding spreads, decisions improve at every level, and the institution no longer waits for a few people at the top to solve each problem. Measuring Progress with Care Progress needs to be checked, but it should be checked fairly. Financial results matter, yet they do not tell the whole story. An institution may report healthy accounts while its people are tired and its mission is slipping. Wise leaders look at the full picture. They ask whether the institution is serving its purpose as well as keeping its books in order. Regular review also helps leaders learn. When a plan works, they can see why. When it falls short, they can correct it early rather than defend it out of pride. In Summary Institutions outlive the people who lead them. That fact places a quiet duty on every leader to leave the organization in better condition than they found it. Sound financial choices made today become the stability that others rely on tomorrow. In the end, business leadership is not about large gestures or bold speeches. Instead, it is a combination of good judgment and honest speech along with the ability to look ahead into the future. When leaders hold to these habits, financial vision stops being a hopeful statement and becomes real progress that people can see and use.
Financial Leadership Icons and the Evolution of Corporate Finance
Building Financial Resilience Corporate finance has changed profoundly over the past several decades. What was once a function focused primarily on accounting accuracy, budget control, and regulatory compliance has grown into something far more central to how organizations are led and how they compete. The tools available to financial leaders have multiplied, the complexity of the environments they navigate has increased, and the expectations placed on them have expanded well beyond the boundaries of the finance department. Running through this evolution is the contribution of the people who have led at the highest levels of financial practice. Financial leadership icons are the individuals whose thinking, decisions, and ways of operating have shaped what corporate finance looks like today and what it continues to become. From Scorekeeping to Strategy For much of corporate history, the finance function was understood primarily as a scorekeeping operation. Its job was to record what had happened, report on it accurately, and ensure that the organization stayed within its financial boundaries. This was important work, but it was reactive and backward-looking by design. Strategy happened elsewhere, and finance provided the numbers. Financial leadership icons began changing this understanding by demonstrating what finance could contribute when it moved from reporting on decisions to actively shaping them. The most prominent icons of financial leadership presented themselves as real strategic partners, offering their perspective on growth and risks much earlier than previously was the case in companies. This shift from scorekeeping to strategy is one of the most significant evolutionary changes in corporate finance. The Rise of Risk as a Financial Discipline Risk has always been present in business, but its management was not always treated as a sophisticated financial discipline in its own right. For much of the twentieth century, risk was handled informally, managed through experience and conservative instinct rather than through structured frameworks and analytical tools. Financial leadership icons changed the conversation around risk significantly. The leaders who shaped modern corporate finance built rigorous approaches to identifying, measuring, and managing risk in ways that allowed organizations to take on more of the right kinds of risk while protecting against the kinds that carried disproportionate downside. This disciplined approach to risk became a defining characteristic of excellent financial leadership and remains central to how the best financial organizations operate today. Building Finance Teams That Could Do More Individual talent only goes so far. The financial leaders who made the most lasting contributions understood that their impact was limited by what their teams could do, and they invested accordingly in building financial functions that were capable of operating at a genuinely high level. This meant developing people, creating clear standards, and building the systems and processes that allowed the finance function to scale its contribution without becoming dependent on any single individual. Financial leadership icons consistently demonstrated this team-building dimension of leadership. They created finance functions that were respected throughout their organizations, that attracted talented people who wanted to develop in them, and that maintained strong performance over time rather than rising and falling with the presence of a single exceptional individual. Navigating Complexity with Clarity One of the defining demands of financial leadership over the past several decades has been the ability to navigate increasing complexity without losing clarity. Global operations, complicated regulatory environments, sophisticated financial instruments, and the speed of information flow in modern markets have all added layers of complexity to the financial leader’s world that their predecessors simply did not face at the same scale. Financial leadership icons have met this complexity not by simplifying it dishonestly but by developing the frameworks, the analytical rigor, and the communicative clarity needed to make sense of it for themselves and for the organizations they led. They demonstrated that complexity is navigable when approached with the right tools and the right habits of mind, and they built those tools and habits into the financial functions they led. Integrity as the Foundation of Financial Leadership Corporate finance has been tested repeatedly by scandals that resulted from financial leaders who prioritized personal gain, short-term performance, or the appearance of success over the honest stewardship of organizational resources and the trust of the stakeholders who depended on them. The contrast between these failures and the standards maintained by genuinely excellent financial leadership has been instructive. Financial leadership icons are distinguished, above almost everything else, by their integrity. Their commitment to honesty, to transparency, and to making decisions that serve the genuine long-term interests of the organizations they lead is what makes their leadership worth studying and emulating. Conclusion The evolution of corporate finance is not simply a story of changing tools, expanding markets, or growing regulatory complexity. It is a story of leadership, of the individuals who shaped what the discipline could be and raised the standards for what financial leadership should deliver. Financial leadership icons leave behind more than track records. They leave behind models of thinking and practice that continue to influence how the next generation of financial leaders approaches the work. Their contribution to the evolution of corporate finance is one worth understanding and building upon.
Searching for a Toronto Web Development Company? 7 Things to Consider
Introduction Choosing a web development company is a significant step for businesses that want to improve their online presence. A professional website can introduce your services, generate inquiries, support online sales, and help establish trust with potential customers. However, selecting a provider requires more than comparing designs or prices. You need a development partner with suitable experience, clear communication, and an approach that matches your business objectives. If you are searching for a Toronto web development company, consider these seven factors before making your final decision. 1. Industry Experience and Portfolio Quality Start by reviewing the company’s previous work. A portfolio helps you understand its design standards, technical capabilities, and experience with different types of websites. Look for projects that demonstrate responsive layouts, intuitive navigation, clear messaging, and useful functionality. If you operate in a specialized industry, ask whether the company has experience with similar requirements. When researching a toronto website developer, focus on evidence of relevant expertise rather than impressive claims alone. Ask how the provider approaches business challenges and whether it can explain the decisions behind its previous projects. This can reveal how well it understands the relationship between website functionality and commercial goals. 2. Range of Development Services Your website may require several services, including design, programming, content management, e-commerce functionality, or third-party integrations. Determine whether the company offers everything your project needs or whether you will have to coordinate multiple suppliers. For example, an online store may need product management, secure payment processing, inventory synchronization, and order notifications. A service business may prioritize booking tools, contact forms, and lead generation. A qualified website developer should help identify the most appropriate features for your requirements. Be cautious about paying for unnecessary extras. The objective is to choose a service package that meets your needs while leaving room for future improvements. 3. Transparent Pricing and Project Scope Pricing is an important consideration, but the cheapest quote may not represent the best value. Request a detailed proposal explaining what is included in the development fee. It should identify the pages, features, design work, testing, revisions, and launch support covered by the agreement. Ask about additional expenses, including hosting, domain renewals, paid plugins, content creation, and maintenance. You should also establish how extra requests will be handled if the project changes after development begins. Clear pricing helps you compare providers fairly and prevents unexpected costs from disrupting your budget. 4. Search Engine Optimization and Performance A website should be designed to provide a strong foundation for search engine visibility. Technical considerations include mobile responsiveness, page speed, logical navigation, descriptive titles, suitable heading structures, and accessible content. Ask the development company how it handles these elements and whether technical SEO is included in the project. Remember that SEO involves more than website development. Search visibility also depends on content relevance, competition, authority, and ongoing optimization. A technically sound website can support your broader marketing strategy, but no responsible developer should guarantee specific rankings without qualification. 5. Mobile Responsiveness and User Experience Many customers browse websites on smartphones, so your website must work effectively across different screen sizes. Check whether the company’s previous projects display properly on mobile devices. Navigation should be simple, text should remain readable, and buttons should be easy to use without unnecessary zooming or scrolling. User experience also involves helping visitors find the information they need quickly. Important details, such as service descriptions, pricing information where applicable, and contact options, should be easy to locate. A website that looks attractive but confuses visitors may struggle to turn traffic into inquiries or sales. 6. Communication, Project Management, and Support Development projects require regular communication between the business and the technical team. Ask how the company manages projects, provides updates, collects feedback, and handles revisions. Confirm who will serve as your primary contact and what response times you can reasonably expect. You should also discuss support after launch. Websites require software updates, backups, security monitoring, and occasional troubleshooting. A dependable web development company toronto businesses choose should clearly explain available support arrangements and the associated costs. Make sure you retain appropriate access to your website, domain, hosting account, and administrative tools. 7. Scalability, Security, and Long-Term Value Your business may expand, introduce new services, or require additional website features in the future. Choosing an appropriate technical foundation can make those changes easier. Discuss whether the website can accommodate additional pages, integrations, languages, products, or customer features as needed. Security should also be considered from the beginning. Depending on the project, this may involve HTTPS, secure forms, controlled administrative access, regular backups, and software updates. Ask how the company handles vulnerabilities and what responsibilities belong to your team after launch. The right provider should help you balance current costs with future flexibility instead of building a website that becomes difficult to maintain. Conclusion Finding the right Toronto web development company requires careful consideration of experience, service offerings, pricing, SEO, user experience, communication, and long-term support. Use these seven factors to compare providers objectively. Review portfolios, ask detailed questions, and request written proposals before committing to a project. Ultimately, the best development partner is one that understands your business, explains its recommendations clearly, and delivers a website designed to serve your customers. A thoughtful selection process can help you avoid unnecessary expenses and establish a stronger foundation for sustainable online growth.
How Driver Assault Claims Can Lead to Rideshare Injury Lawsuits
An Uber passenger who is assaulted by a driver may face consequences that continue long after the ride ends. Physical injuries, emotional trauma, medical treatment, and missed work can create a difficult path toward recovery, particularly when questions arise about who should be held responsible. In St. Louis, MO, someone considering an Uber driver assault lawsuit may need to look beyond the driver’s conduct and examine the circumstances surrounding the rideshare company’s involvement. The strength of a claim can depend on the available evidence, the nature of the injuries, and the parties connected to the incident. Understanding those factors early can help an injured passenger protect important records, evaluate potential sources of compensation, and make informed decisions about pursuing a legal claim. Why Assault Claims Matter A driver assault lawsuit can address losses that criminal court does not cover. Criminal cases focus on punishment, while civil claims seek payment for medical expenses, therapy, lost wages, pain, and emotional distress. A passenger may also examine whether company screening, supervision, or safety procedures contributed to the incident. These cases require proof connecting the assault with measurable harm and identifying each party that may owe compensation. Identifying Responsible Parties The driver may bear direct responsibility for sexual violence, threatening conduct, or negligent actions that caused injury. Company liability can arise from inadequate screening, weak reporting systems, poor supervision, or failures involving known safety concerns. Another passenger, business, or property owner might share fault under certain facts. Legal responsibility depends on each party’s conduct, relationship to the trip, and connection to the passenger’s injuries. Driver Conduct An assault can support a civil claim even if prosecutors do not bring charges. Criminal and civil proceedings use different proof standards, so one case does not automatically control the other. A conviction may strengthen the injured person’s position, but testimony, medical records, messages, and other evidence can establish liability on their own. The civil process may address treatment costs, reduced income, physical suffering, and psychological effects. Evidence That Supports a Claim A prompt report creates an important starting point. Police records, emergency department notes, photographs, surveillance video, trip details, text messages, and witness accounts may confirm the event. Medical providers should document symptoms, diagnoses, treatment plans, and functional limits. Therapy records can describe panic, insomnia, avoidance, or post-traumatic stress symptoms. Screenshots, receipts, pay records, and travel expenses can help prove the financial impact. How Rideshare Insurance May Apply Coverage often depends on the driver’s status during the trip. A personal policy may apply before a ride request, while another policy may apply after acceptance or pickup. Limits, exclusions, state requirements, and disputed facts can change the amount available. Insurers may seek recorded statements, authorizations, or medical histories. An injured passenger should review these requests carefully before providing information or signing any documents. Injuries and Financial Losses Physical harm may involve bruising, lacerations, fractures, head trauma, or sexually transmitted infections. Some conditions appear immediately, while others become clear days later. Psychological injuries may include anxiety, depression, nightmares, fear of transportation, or difficulty concentrating. Compensation can include hospital charges, medication, counseling, lost earnings, diminished future income, transportation costs, and continuing care. A damages record should include both visible symptoms and lasting limitations. Deadlines and Filing Steps Each state establishes a filing deadline for injury litigation. Different periods may apply to minors, public entities, uninsured parties, or claims involving special notice rules. Missing the applicable date can permanently bar recovery. After an incident, the passenger should seek medical attention, report the conduct, preserve electronic records, and maintain an expense log. A lawyer can assess deadlines, identify defendants, issue evidence requests, and prepare court documents. Why Legal Guidance Helps Rideshare assault cases often involve multiple insurers, incomplete accounts, disputed driver status, and sensitive medical evidence. Counsel can compare trip records with witness statements, request surveillance footage, examine safety policies, and calculate future treatment needs. Legal representation also limits direct contact with claims adjusters while recovery continues. That support reduces avoidable mistakes and helps ensure that settlement discussions reflect the full extent of physical, emotional, and financial harm. Conclusion Assault during a rideshare trip can produce lasting consequences that extend well beyond the original event. A civil action may address medical treatment, counseling, lost income, physical pain, emotional trauma, and future care. Evidence should be preserved before digital records are deleted, and filing deadlines require immediate attention. Injured passengers should avoid signing releases or giving recorded statements until the claim has been reviewed by qualified counsel familiar with personal injury and rideshare liability law.
DiveIn Media Secures Investment to Advance Influencer Campaign Reporting
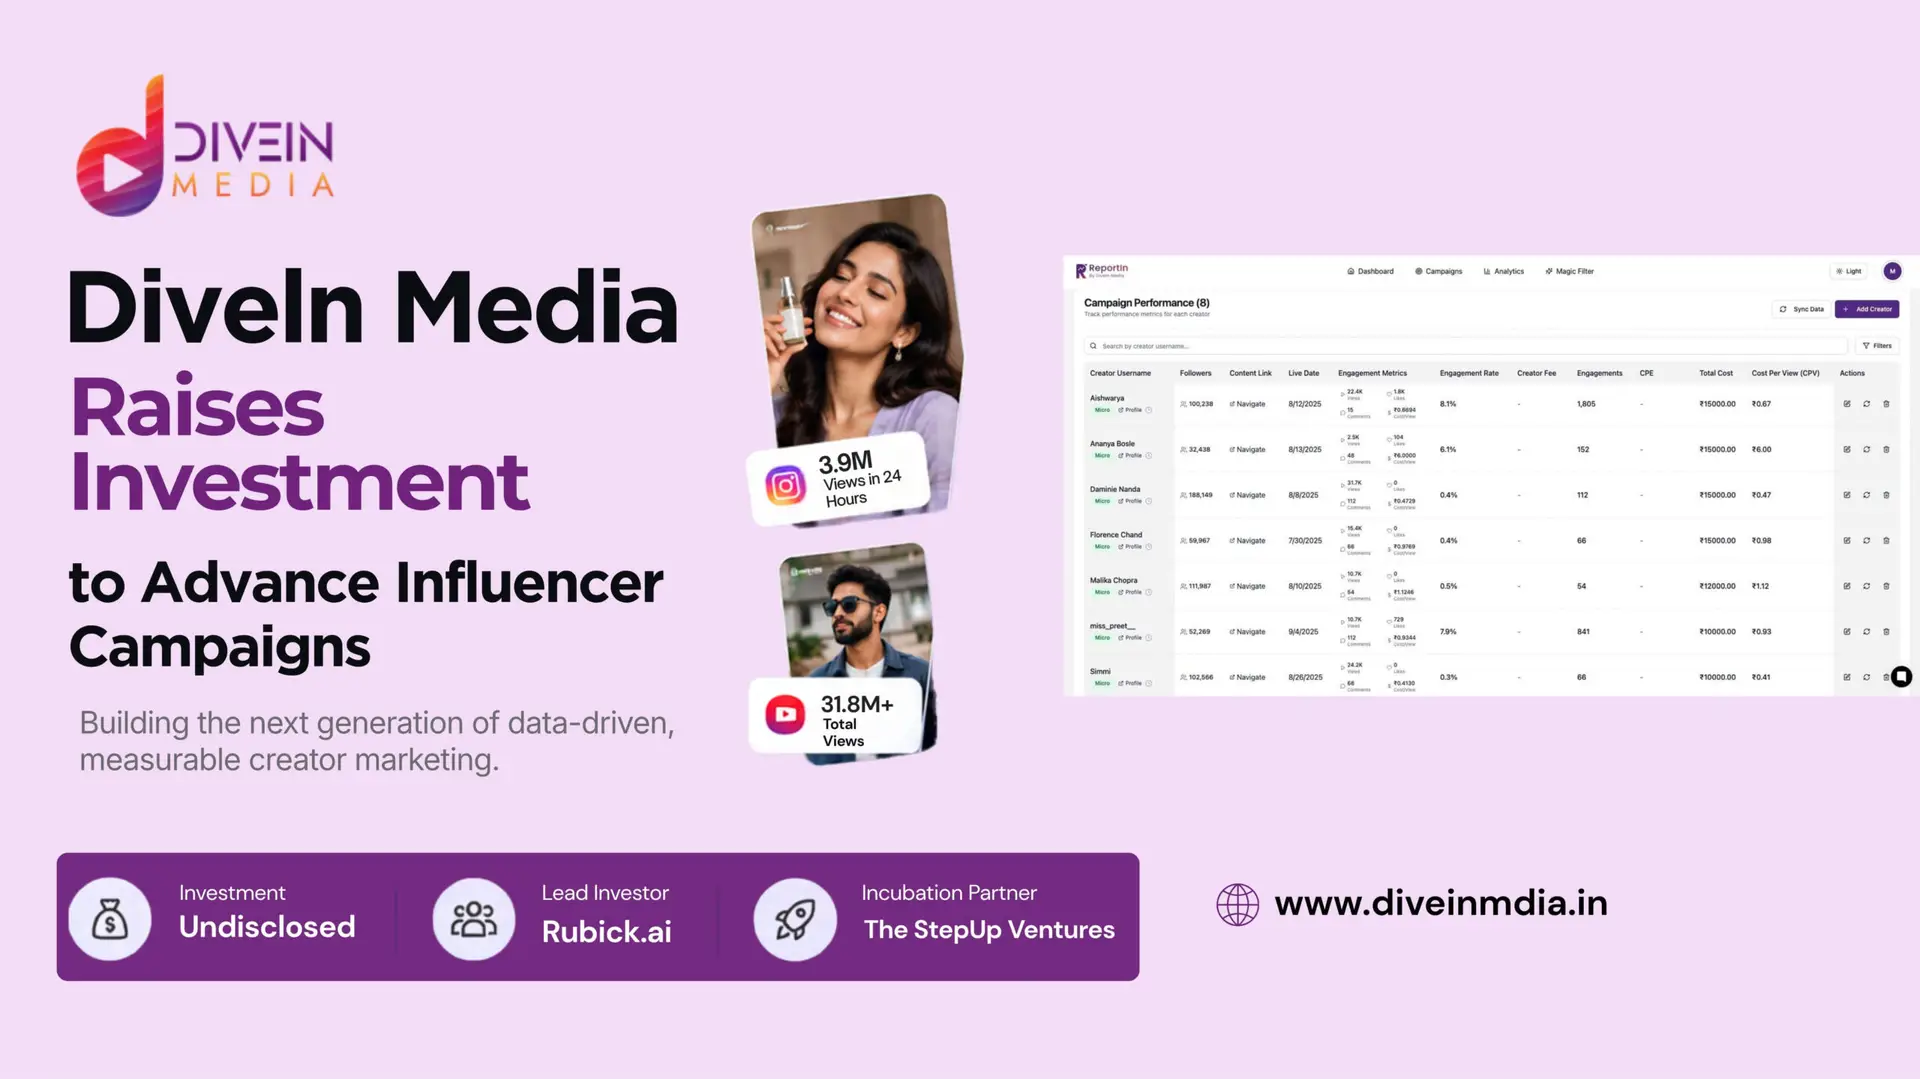
Rubick.ai leads the investment round, with former IPL player Bharath Chipli among the investors; Stepup Ventures supports DiveIn Media as an incubation partner. Bengaluru, India: DiveIn Media, an Influencer Marketing Platform, has secured an undisclosed investment round led by Rubick.ai to accelerate the development and adoption of ReportIn, its campaign reporting platform for creator-led marketing. Former IPL player Bharath Chipli, who played for Royal Challengers Bengaluru (RCB), Deccan Chargers and Delhi Daredevils, is also among the investors in the round, while The Stepup Ventures is supporting the company as an incubation partner. DiveIn Media has served 100+ brands across 12+ industries, including multiple MSMEs and 20+ enterprise companies, over the past four years. Its creator campaigns have generated an estimated 1.2 billion+ views, supported by a network of more than 1,00,000+ creators, reflecting the scale of creator-led work delivered for brands across the country. The investment comes as influencer marketing evolves from an experimental brand-building channel into a more significant component of marketing strategy. As companies increase their investments in creators, there is a growing need to measure campaigns with greater consistency, transparency and accountability. Building the Reporting Layer for Influencer Marketing Brands today can work with hundreds of creators across multiple platforms and campaigns. While metrics such as views, reach, likes, comments and engagement provide useful indicators, campaign information is often fragmented across different sources, making it difficult for marketing teams to develop a unified view of performance. “Influencer marketing is no longer just about visibility. Brands want confidence in the decisions they make, clarity on the outcomes they achieve and a more reliable way to understand the value created through creator partnerships,” said Priyanka Joshi, Founder of DiveIn Media. “ReportIn is being developed to support that shift.” DiveIn Media is developing ReportIn to address this gap. As brands move from one-off influencer collaborations towards larger and more repeatable creator programs, consistent reporting can help marketing teams understand what worked, compare performance across campaigns and creators, and make more informed decisions about where to allocate future budgets. In its campaigns, DiveIn Media has seen micro and nano creators deliver strong reach and engagement for brands, particularly when they connect with audiences in relevant languages and communities. For one of South India’s top FMCG companies, a campaign with vernacular nano and micro creators generated 31.8 million-plus views and 292,700 active engagements. For one of India’s leading fashion brands, 124 nano and micro creators attended a store launch and created online content to build awareness. The campaign reached 3.9 million views within 24 hours, generated 40,700 active engagements and was followed by positive store footfall during the Raksha Bandhan period. These campaign results illustrate why brands are paying closer attention to creator selection and measurement. Views and engagements help show audience response, while consistent reporting can help brands compare activity and assess its contribution to campaign objectives. The company’s longer-term ambition is to help transform influencer campaign reporting from a largely fragmented, post-campaign exercise into an ongoing intelligence layer that supports how brands plan, evaluate and scale their creator partnerships. From Influencer Activity to Influencer Accountability The broader creator economy is entering a new phase. For brands, the question is increasingly shifting from “How many creators should we work with?” to “What business value are these creator partnerships generating?” Answering that question requires more than individual campaign metrics. It requires infrastructure that can organise campaign data, establish consistent measurement and turn performance information into insights that marketing teams can act on. DiveIn Media believes ReportIn can become part of that infrastructure. With Rubick.ai leading the investment round, Bharath Chipli participating as an investor, and The Stepup Ventures supporting the company through incubation, DiveIn Media plans to build ReportIn into a platform that helps brands bring greater clarity, intelligence and accountability to creator marketing.