
A trade can look profitable on the screen and still leave you with a much smaller amount in your pocket. The reason is simple: buying and selling investments involves costs. At the same time, money placed in a fixed deposit follows a completely different return pattern. Looking at both sides of the calculation can make financial decisions more realistic.
Profit is not the same as the price difference
Let’s assume you acquire shares for ₹50,000 and subsequently sell them for ₹55,000. The ₹5,000 difference first looks to be your profit. But the actual result depends on the expenses attached to the transactions.
Brokerage, taxes and other applicable charges can reduce the amount you finally receive. This is why calculating the expected cost before placing an order can be useful, particularly when the expected gain is relatively small.
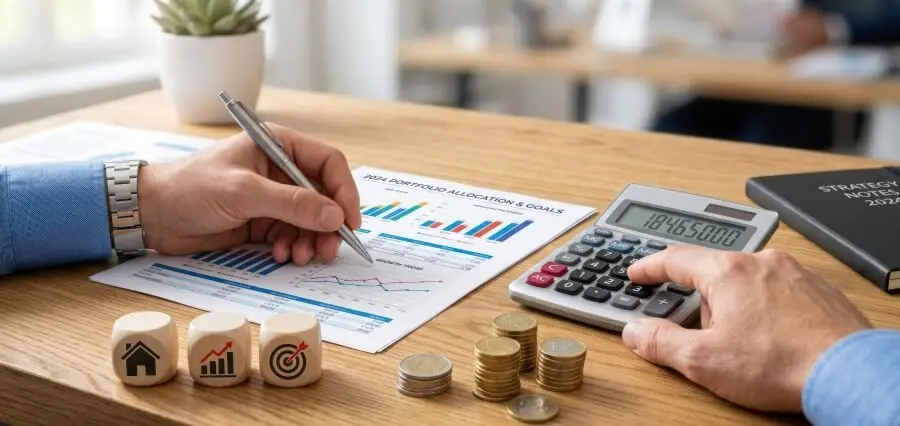
A brokerage calculator provides a practical way to estimate these expenses. By entering relevant trade details, investors can get an idea of the brokerage and other applicable charges associated with a transaction. That makes it easier to judge whether a trade still makes sense after costs are considered.
Why small charges deserve attention
Trading costs can become more noticeable when an investor makes frequent transactions. A charge that appears insignificant on a single order can have a much larger effect when repeated across numerous trades.
This does not mean investors should avoid trading simply because charges exist. It means the decision should be based on the net outcome rather than the headline buying and selling prices.
For example, someone targeting a modest return should know exactly how much of that return may disappear through applicable costs. Having the numbers beforehand can also prevent unrealistic profit expectations.
Returns need a different perspective
Investors also need to understand that not every financial decision revolves around market price movements. Fixed deposits, for instance, offer returns based on the deposit amount, interest rate and chosen tenure.
An FD calculator helps estimate how much a fixed deposit could grow over a particular period. Instead of asking whether a share price might rise, the investor can examine the maturity amount and interest generated under the selected deposit terms.
That comparison can be useful when deciding where surplus money should go. Equity investments may offer the possibility of market linked returns, but they also involve market risk. A fixed deposit provides a more predictable calculation based on the applicable interest rate and tenure.
Put the two calculations together
The interesting part is not choosing one calculator over the other. It is understanding what each calculation tells you.
For a proposed stock transaction, work out the purchase value, expected selling value and associated trading costs. What remains gives you a more useful picture of the potential outcome.
For a fixed deposit, consider the amount invested, interest rate and tenure to estimate the maturity value. You can then compare the potential outcome with your financial objective and time horizon.
Neither calculator can tell you exactly what will happen in the future. A brokerage calculator does not predict whether a stock will rise, while an FD calculator does not measure inflation or changes in your personal circumstances.
What they can do is remove some guesswork. And that matters. Good investing is not simply about finding an opportunity that looks profitable. It is about understanding what you put in, what you may receive back and what stands between those two numbers.